Short answer: Yes, owning a home can still build wealth in 2026, but more slowly than it did when rates were near 4%, so how long you plan to stay matters more than today's rate.
Video recorded October 27, 2026 (about 2 minutes). Mortgage rate data as of October 29, 2026 (Freddie Mac); Newtown sales data through October 22, 2026 (SmartMLS). Mortgage rates change every week.
A recent Realtor.com article asked a question I hear all the time: are homes still a good way to build wealth? My honest answer is that it's complicated. Here's the plain-words version of what I cover in the video, with the numbers behind it.
What changed over the past decade?
For about a decade after the Great Recession, money was cheap. From 2009 through 2021, the 30-year mortgage rate averaged roughly 4%, according to Realtor.com (October 16, 2026). Low rates, rising home values and easy access to credit built a lot of wealth for people who owned homes and invested in the stock market. Realtor.com reports that homeowners' equity tripled over that stretch.
Today it's a different game.
Where are mortgage rates today?
The average 30-year fixed mortgage rate was 7.24% nationally for the week of October 29, 2026, according to Freddie Mac's Primary Mortgage Market Survey. That's down from 7.32% the week before and from 7.40% on October 15, which Realtor.com called the highest since November 2023.
Higher rates matter because more of each early payment goes to interest. On Realtor.com's example of a roughly $299,400 starter home with 10% down, a buyer at 7.40% pays down about $14,760 of principal in the first five years, compared with about $25,740 at 4% (Realtor.com, October 16, 2026).
Why not rent and invest the difference?
It's a fair argument. Realtor.com found that buying a starter home costs more each month than renting one in all 50 of the largest U.S. metros, with renters saving about $960 a month, or more than $11,000 a year (Realtor.com analysis, October 16, 2026).
The stock market has also had a strong run. The S&P 500 returned 26.3% in 2023, 25% in 2024 and 17.9% in 2025, including dividends, as reported by Realtor.com. Past returns aren't a promise, though. Vanguard projects U.S. stock returns of only about 4.2% to 6.2% a year over the next decade, which Realtor.com notes is roughly on par with historical home appreciation.
For some people, renting really is the right answer. But there's one big catch: you actually have to invest the difference, every month, for years. Realtor.com economist Jiayi Xu put it this way: it "could work well as long as the person is very self-disciplined about actually investing that money consistently instead of spending it."
How does a mortgage build equity?
That's where owning is different. When you own a home, every payment puts money toward an asset you live in. You get the use of the home, you pay down the loan, and you have the potential for appreciation over time. A fixed-rate mortgage also locks in the principal-and-interest part of your payment.
At today's rates, that equity builds more slowly in the early years. So the question isn't only "what's my rate?" It's "how long will I be here?"
Why does the 5, 10 and 20-year view matter?
I'm not saying everyone should run out and buy a house tomorrow. I'm saying the decision looks different over 5 years than it does over 10 or 20. The longer you stay, the more principal you pay down and the more time the home has to appreciate.
As I say in the video: "Real estate isn't just about the interest rate. It's about leveraging equity, appreciation, lifestyle, and time."
What about Newtown?
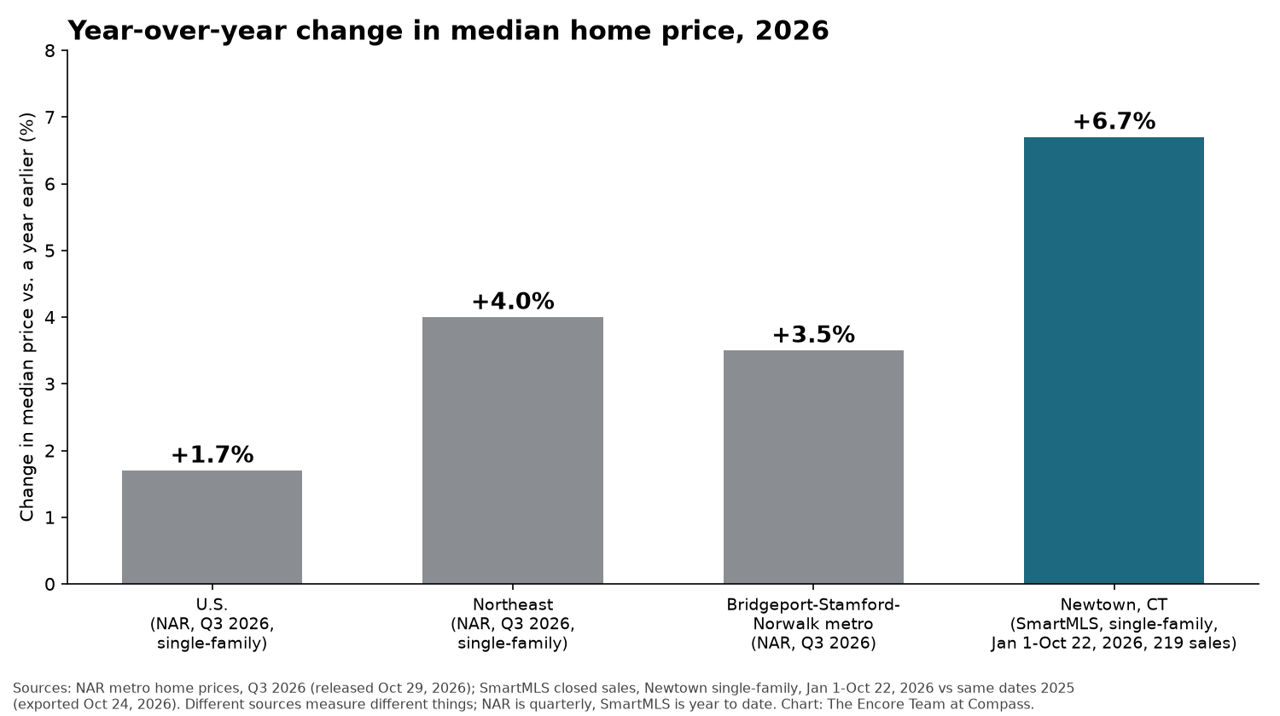
Locally, in Newtown, prices have held up even with higher rates. The median single-family sale price in Newtown was $720,000 from January 1 to October 22, 2026, up 6.7% from the same period of 2025, based on 219 closed single-family sales in SmartMLS (exported October 24, 2026). Past price gains don't promise future ones, and every home's value depends on its condition, location and features.
Frequently asked questions
Is buying a home still a good investment in 2026?
It can be, especially if you plan to stay for many years. At 7.24% (Freddie Mac, October 29, 2026), equity builds more slowly in the early years than it did at 4%, so your time horizon matters more than ever.
Is it cheaper to rent or buy right now?
Month to month, renting is usually cheaper. Realtor.com found renting a starter home was about $960 a month cheaper than buying in each of the 50 largest U.S. metros (October 16, 2026).
Does "rent and invest the difference" work?
Only if you invest the difference consistently, every month, for years. Recent stock returns were strong, but Vanguard projects about 4.2% to 6.2% a year over the next decade, and past returns aren't a promise.
How much equity do you build in the first five years of a mortgage?
On Realtor.com's example of a roughly $299,400 home with 10% down, about $14,760 of principal is paid down in five years at 7.40%, versus about $25,740 at 4% (Realtor.com, October 16, 2026).
What are mortgage rates today?
The 30-year fixed averaged 7.24% for the week of October 29, 2026, per Freddie Mac. Rates change weekly, so check freddiemac.com/pmms for the latest number.
Want to see your own numbers?
If you're trying to figure out which side of the rent-or-own question makes sense for you, that's a conversation I'd love to have. Start with a free market analysis to see where your current home stands, or call or text me at 203-727-8621.
This post is general information, not financial, investment or tax advice. Talk with a financial advisor about your own situation.
Sources and data note
- Freddie Mac, Primary Mortgage Market Survey, week of October 29, 2026: 30-year fixed 7.24% (7.32% the week of October 22; 7.40% the week of October 15). https://www.freddiemac.com/pmms
- Allaire Conte, "Cheap Money Built a Generation of Wealth. What Happens to Housing When It's Gone?", Realtor.com, October 16, 2026: rent-vs-buy gap (about $960 a month in the 50 largest metros), the $299,400 starter-home principal example, 2009–2021 rate averages, S&P 500 returns (as reported) and Vanguard's 10-year projection (as reported). https://www.realtor.com/news/trends/high-interest-rates-wealth-building-homes-stocks/
- SmartMLS, Newtown single-family closed sales, January 1 to October 22, 2026 versus the same period of 2025 (219 sales in 2026), exported October 24, 2026.
- "It's complicated" is my own phrase, not the article's. Video recorded October 27, 2026. Figures checked October 28, 2026. Rates change weekly.